In a market shaped by increasing regulation and more complex client needs, choosing the right life company has never been more important. Life policies are long-term structures that often support wealth planning across generations. Exiting early can create tax consequences and disrupt carefully designed plans.
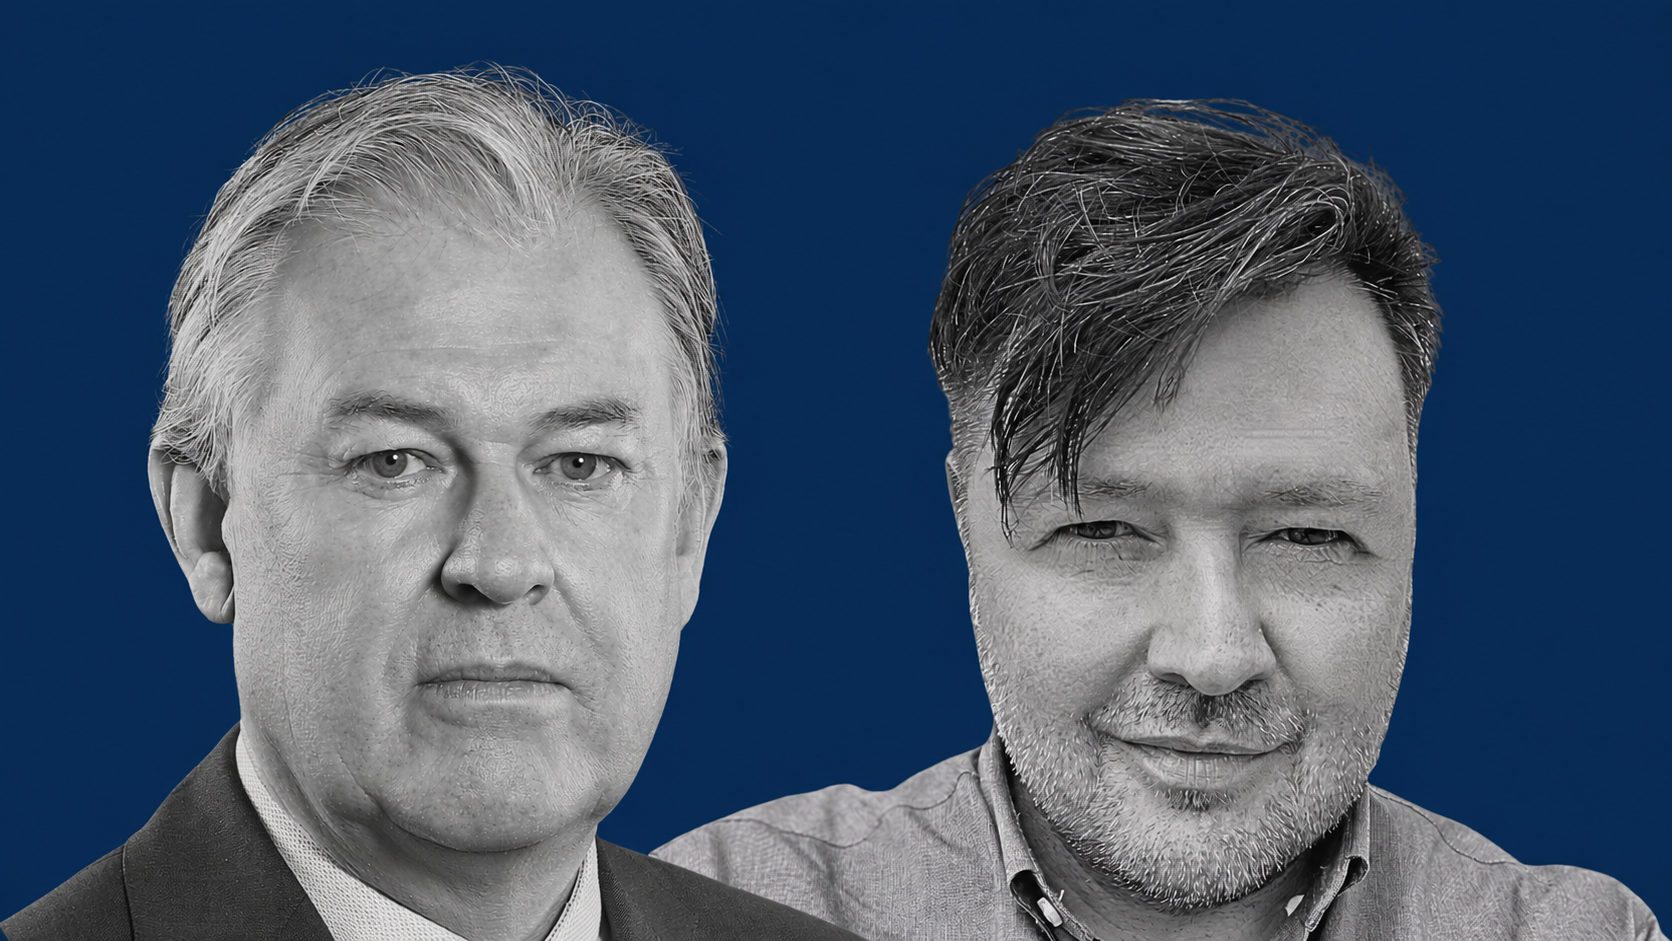
In this discussion Stephen Atkinson, Global Head of Sales and Marketing at Utmost Group and Investment Adviser Publisher Gary Robinson, both pictured above L-R, talk about what advisers and their clients should look for when selecting a life company and how the international wealth insurance market is evolving.
________________________________
Gary Robinson: Stephen, Utmost has built a reputation for strength and reliability in the international cross-border planning and HNW market. What do you think sets it apart?
Stephen Atkinson: I have spent more than 30 years in this industry and for me it comes down to two things. First, financial strength. Second, having the expertise to deal with the real-world situations advisers and clients face every day.
Clients are not choosing a life company for the next couple of years. They are making decisions that could last decades, so they need confidence that the provider they choose will still be there, still investing in capabilities and still supporting them in the future.
Utmost’s latest half-year results show assets under administration of over £100 billion, record inflows and client retention of 93%. Alongside that, Utmost has built teams with deep technical expertise that support everything from straightforward cases to highly complex international planning situations.
GR: What do you mean by complex cases?
SA: Twenty years ago international planning was often the exception. Today it is becoming far more common.
We see clients living in one country, investing in another and planning for family members based somewhere else entirely. Many have trusts or corporate structures in place. Others are planning future moves. Every one of those decisions can bring tax, regulatory and succession considerations.
The reality is that advisers need a provider that understands those moving parts. One of Utmost’s strengths is the depth of technical expertise available across different markets and jurisdictions.
GR: I certainly see more of that in the industry. People’s lives seem more international than ever.
SA: They are. Circumstances change, residency changes, family situations change and investment priorities change. A life company needs the expertise and flexibility to adapt alongside the client.
GR: If an adviser is comparing providers, where should they start?
SA: Strip away the marketing and focus on the fundamentals. How strong is the business financially? Is it investing in its future? Does it have the expertise to support clients when their circumstances change? Those questions matter far more and this is where Utmost believes its track record speaks for itself.
GR: So, scale is an important consideration?
SA: Absolutely.
When you are recommending a provider, why take an unrewarded risk? If a client is placing a significant proportion of their wealth into a long-term structure, they need confidence in the company behind it. Each of Utmost’s insurance companies holds a Fitch A+ Insurer Financial Strength rating. Importantly, those ratings sit at the individual insurance company level.
Some providers may rely on a parent company rating or broader group support. Advisers should understand the difference because clients are increasingly asking those questions. When you combine those ratings with Utmost’s scale (more than £100 billion in assets under administration) and strong solvency levels, it gives an indication of the resilience of the business.
GR: Another thing advisers often ask about is long-term committment. Why does that matter so much?
SA: Because issuing a policy is only the beginning. Clients may hold these structures for twenty or thirty years. During that time they might change investment manager, switch custodian, move country or update their succession plans.
Supporting that properly requires ongoing investment and that remains a key focus for Utmost. It takes good people, strong systems and deep technical expertise. That does not happen by accident.
Importantly, international wealth insurance is not a sideline for Utmost. It is our core focus and what we do every day. We have built deep expertise across jurisdictions, tax frameworks and client needs over many years. Combined with the scale of the Utmost business and the significant investment we continue to make, that allows us to provide the institutional level of governance, oversight and resilience that advisers and clients increasingly expect from a long-term provider.
GR: Those in the adviser services and wealth transfer planning world, certainly seem to expect more than they did in the past.
SA: Clients expect good digital services. Advisers expect efficient processes. Regulators expect high standards. Cyber security expectations are significantly higher than they were ten years ago.
Utmost continues to invest heavily in technology, operations and service because standing still is not an option in today’s market.
GR: Cost is always part of the discussion. How do you respond when clients question charges?
SA: It is a fair question and advisers should ask it. Utmost’s pricing is competitive within the marketplace, but we have never set out to be the cheapest option. Running an international life company is expensive. You need strong capital reserves, governance, compliance, tax expertise, technology and cyber security. You need experienced people supporting advisers and clients across multiple markets and jurisdictions.
Those things matter, particularly when markets become volatile or regulations change.
GR: Price needs to be viewed alongside value?
SA: Exactly. Pricing should be considered in the context of what clients actually need and receive.
A crucial question. Can the provider support a change in residency? We have partners who may have clients moving from the UK to France, from Brazil to Portugal or from Asia to Australia. How will this work? Can a change of investment manager or custodian be facilitated? Does the insurance company provide ongoing tax reporting? Can they support succession planning over time?
Utmost continues to invest in all of these areas because they are central to delivering good long-term client outcomes.
The cheapest option today is not necessarily the best option ten years from now. Charges should be assessed alongside other considerations such as product features and the client’s individual needs.
GR: Looking ahead, what do you think advisers need to prepare for?
SA: One of the biggest changes is the growing demand for international planning. Clients are becoming more mobile, family structures are becoming more complex and expectations continue to increase.
We are also seeing growing interest in alternative investments, continued advances in artificial intelligence and increasing focus on cyber security and operational resilience. For Utmost, that means continuing to invest in our people, technology and capabilities so that we can support advisers and clients as the market evolves.
GR: International mobility is certainly becoming a bigger factor for many clients.
SA: I agree. Cross-border planning is not getting simpler. It is becoming more complex. That is why choosing the right life company matters. Advisers need a provider that can support clients through changing circumstances, changing regulations and changing markets. Utmost has spent more than a decade building the scale, expertise and financial strength needed to do exactly that. The advisers who get those decisions right today are better placed to create positive long-term outcomes for their clients.