Skip to content
International Adviser
  • Contact
  • Subscribe
  • Regions
    • United Kingdom
    • Middle East
    • Europe
    • Asia
    • Africa
    • North America
    • Latin America
  • Industry
    • Tax & Regulation
    • Products
    • Life
    • Health & Protection
    • People Moves
    • Companies
    • Offshore Bonds
    • Retirement
    • Technology
    • Platforms
  • Investment
    • Equities
    • Fixed Income
    • Alternatives
    • Multi Asset
    • Property
    • Macro Views
    • Structured Products
    • Emerging Markets
    • Commodities
  • IA 100
  • Best Practice
    • Best Practice Awards
  • Media
    • Video
    • Podcast
  • Directory
  • My IA
    • Events
    • IA Tax Panel
    • IA Intermediary Panel
    • About IA

ANNOUNCEMENT: Read more financial articles on our partner site, click here to read more.

Using Qnups in retirement wealth planning

By International Adviser, 23 Jan 17

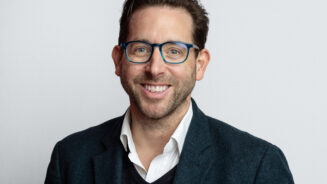
In this first instalment of a two-part series on Qnups in wealth planning, director of Isle of Man-based pension provider Optimus, Martin Hall says the retirement solutions are great for those restricted by the dwindling lifetime allowance cap.

Looking up a generation, people are living longer and middle-aged retirees commonly now find their own parents are in need of specialist, and costly, long-term care.

People in their 50s and 60s could, conceivably, be facing a much higher financial burden than ever before for both their parents and children, and far beyond that which could be covered by state or registered pensions. So, sensibly, a long-term rainy day fund is created to cover these eventualities but if that rainy day never comes the safety net may not be required. Where that fund is a Qnups then at least it can eventually be passed on without a painful IHT hit.

Pension warning

There is a gentle health warning, though. Put simply, any Qnups must be real a pension arrangement.

Using the structure of a Qnups for short-term IHT planning alone is likely to fall foul of a number of anti-avoidance tests.

Pension saving does not, almost by definition, tend to start in old age, ill-health (or both) nor does it tend to swallow up the majority of an individual’s estate so, where characteristics such as these exist, be alert to the possible pitfalls.

Those seeking higher levels of retirement income need a different state-approved alternative and Qnups could well be it.
Pages: Page 1, Page 2, Page 3

Tags: Lifetime Allowance | Qnups

Share this article
Follow by Email
Facebook
fb-share-icon
X (Twitter)
Post on X
LinkedIn
Share

Related Stories

  • Insights

    Would a wealth tax work?

    Jersey flag

    Latest news

    Jersey actions changes to financial services framework

  • Crypto regulation

    Latest news

    FCA launches ‘landmark’ crypto regime

    Financial planning

    FEIFA partners with Tax Innovations to provide members with cross-border expertise


NEWSLETTER

Sign Up for International
Adviser Daily Newsletter

subscribe

  • View site map
  • Privacy Policy
  • Terms and Conditions
  • Contact

Published by Money Map Media – part of G&M Media Ltd Copyright (c) 2024.

International Adviser covers the global intermediary market that uses cross-border insurance, investments, banking and pension products on behalf of their high-net-worth clients. No news, articles or content may be reproduced in part or in full without express permission of International Adviser. Site managed by Furness Media